Introduction
When cash is tight, small wholesalers in British Columbia must treat receivables aging not as an accounting report but as a triage tool. This article explains how to read your aging, decide who to call first, and take practical steps that preserve customer relationships while improving short-term cash flow. You will learn how to prioritise customers by age and dollar value, which contacts and tactics are most effective at each stage, and what escalation options exist in BC — from payment plans to invoice factoring and legal remedies through the Personal Property Registry or small claims court. The guidance below balances collection urgency with cost and relationship risk so you can act quickly and confidently when funds are running low.
Understand your aging report and priorities
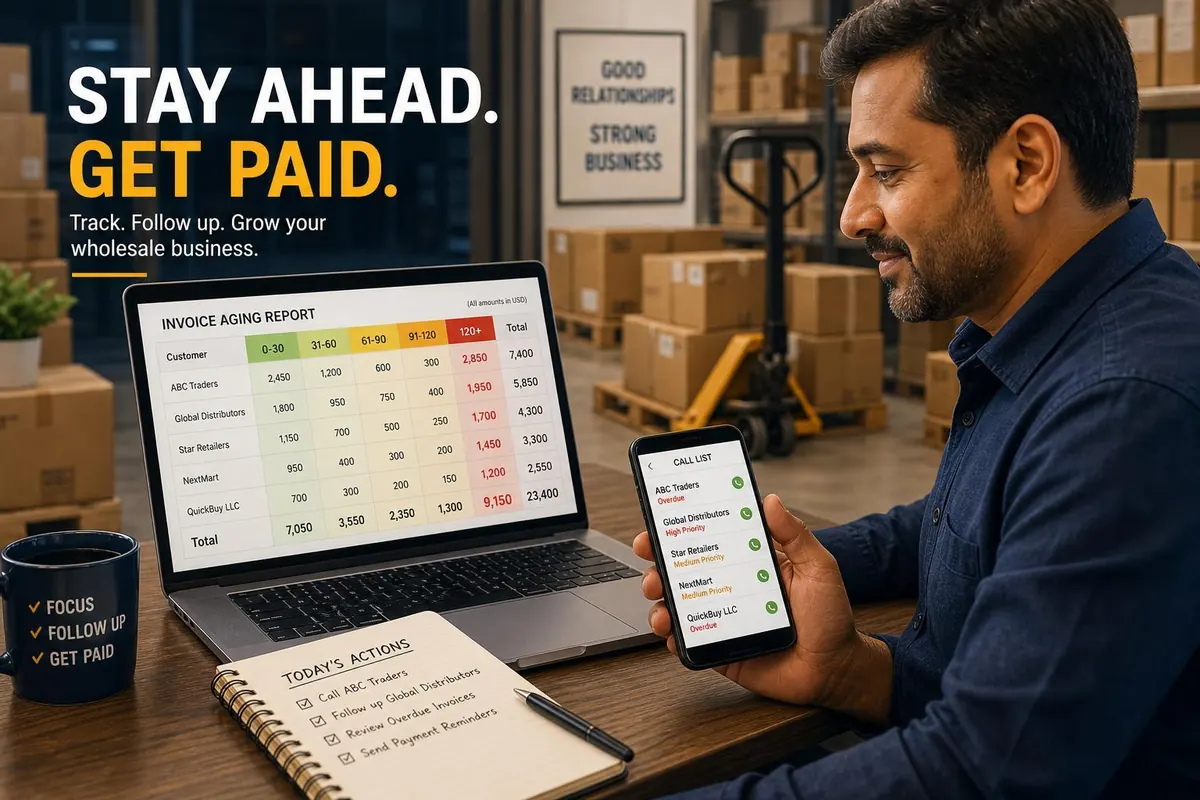
Start by running a current receivables aging sorted by customer, total balance, and days outstanding. Typical buckets are 0-30, 31-60, 61-90 and 90+ days. Use these criteria to prioritise:
- Dollar impact: balances that, if unpaid, create the largest immediate working capital gap. For many small wholesalers, overdue amounts above $5,000 to $10,000 should be flagged as high priority.
- Age and trend: a 31-60 day balance that is steadily increasing may become more problematic than a one-off 61-90 day small invoice.
- Customer risk and leverage: consider payment history, open orders, and whether you hold a security interest through BC’s Personal Property Registry (PPR) or have a retain-title clause in your terms.
- Profitability and cost to collect: chasing a $200 past-due invoice that costs $100 in labour and fees is usually not worthwhile; set a sensible internal threshold for collection effort.
Who to call first and why
When cash is tight, make calls in this sequence to maximise recovery and preserve key relationships:
- Top-dollar, short-term at-risk accounts: customers with the largest overdue balances and pending orders. Your leverage: upcoming shipments or stop-credit notices. Call the accounting or purchasing manager, then the owner if required.
- Strategic ongoing customers: smaller overdue amounts but high lifetime value. Use a softer approach - friendly reminders and payment plans to avoid losing future business.
- Long-overdue or disputed accounts: older than 90 days or with active disputes. Escalate to the owner or credit manager and consider written demand before external collection.
- Small-dollar problem accounts: balances under your cost-to-collect threshold. Decide whether to write off, bundle to a collections agency, or accept part-payment offers.
Always prioritise contacts who can authorise payment decisions: accounts payable supervisors, procurement managers, or owners. For speed, call first, follow up with email summarising the conversation, and attach the invoice and ledger.
How to structure collection calls and negotiations
Effective calls are short, factual and offer clear options. Use a three-step structure:
- Confirm: “I’m calling about invoice #12345 for $8,200 due July 3. Are you able to confirm receipt of the goods and invoice?”
- Listen and diagnose: note reasons for delay - dispute, cash flow, or internal processing. Understanding the cause determines the response.
- Offer options and get commitment: propose specific remedies: full payment by X date, a two-part payment (50% now, 50% in 30 days), a short-term credit card transaction, or a replacement of pending shipments with COD terms.
Document the agreed timeline and follow up with an email. Helpful negotiation points:
- Offer a small early-payment discount only if it improves immediate cash - for example 1% on invoices paid within 7 days, capped so you don’t erode margin.
- Use future orders as leverage: require partial prepayment or payment on delivery for the next order.
- For recurring disputes, create a simple dispute resolution form so issues don’t delay payment.
Cash alternatives and escalation options
If customer calls and negotiated plans are insufficient, choose escalation based on expected recovery and cost:
- Invoice factoring or receivables financing: sell overdue invoices or your receivables book to a factor for immediate cash. Fees vary - often 1% to 5% of invoice value per month depending on credit risk and contract terms. Good when you need rapid funds and can accept the fee.
- Collections agencies: contingency fees typically 15% to 30% but they take the collection burden. Use for long-overdue accounts where internal collection has failed.
- Legal remedies in BC: file a claim through Small Claims Court (limit about $35,000) or register security at the Personal Property Registry (PPR) to preserve your rights. Legal steps are slower and carry costs, so reserve for high-value accounts or clear breaches.
- Bank and credit options: talk to your bank about a short-term line of credit or overdraft to bridge cash flow. Present your aging report and customer commitments to improve access.
Receivables aging action table
| Aging bucket | Priority | Recommended first action | Escalation / timing | Example (CAD) |
|---|---|---|---|---|
| 0-30 days | Low to medium | Friendly reminder call and emailed statement | Recheck in 7 days if unpaid | $500 - $5,000 |
| 31-60 days | Medium | Call accounts payable; offer payment plan or card payment | Hold new shipments until resolution; escalate in 10-14 days | $1,000 - $8,000 |
| 61-90 days | High | Owner-level contact; formal demand email and payment options | Consider factoring or collections if no response in 7 days | $5,000 - $15,000 |
| 90+ days | Highest | Final demand, hold against PPR lien, collections or legal action | Engage agency or small claims within 14-30 days depending on value | $2,000 - $50,000+ |
Conclusion
When cash is tight, an effective receivables aging process helps you call the right customers first and use the right mix of persuasion and leverage. Start by segmenting balances by age, dollar value and customer importance, then prioritise calls to those accounts that create the largest immediate cash shortfall or where you have the most leverage. Structure calls to confirm facts, diagnose the cause, and secure a concrete payment commitment, then document everything. If internal collection stalls, consider factoring, collections agencies, or legal remedies through BC’s PPR and small claims system, weighing cost against likely recovery. Acting quickly, consistently and with a clear escalation plan protects cash flow and preserves valuable customer relationships.